How to Get a Home Loan?
Bank vs Housing Finance Company: Which Loan Is Better?
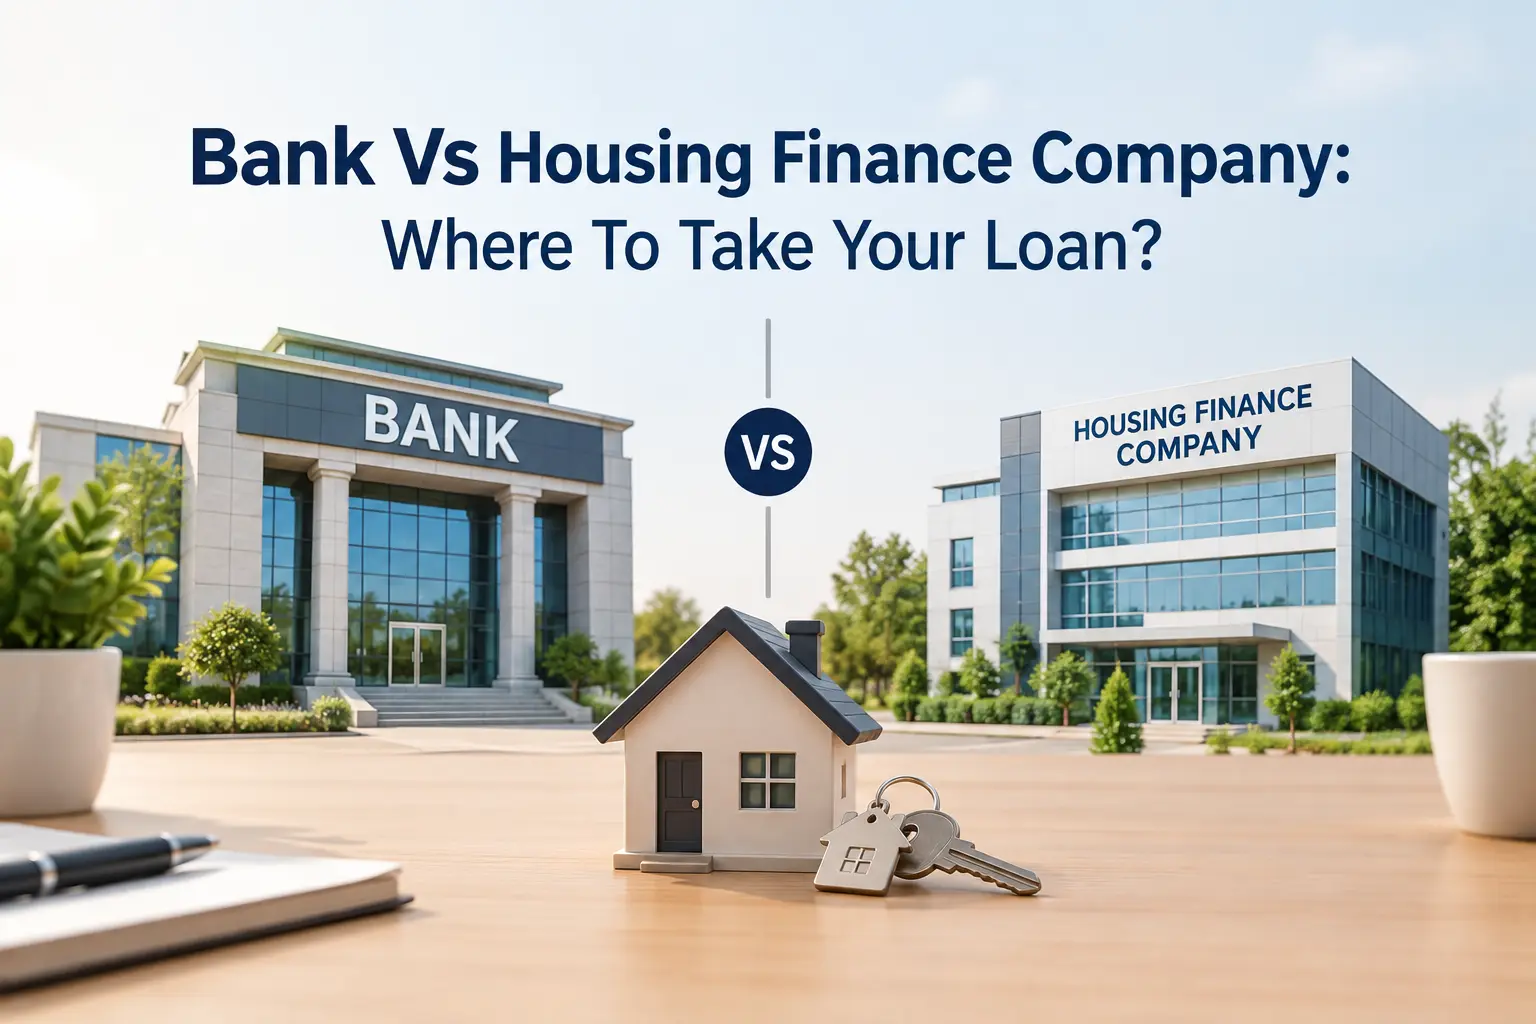
Picking a home loan provider can shape your budget for a long time, even for two decades. You will usually see banks and Housing Finance Companies, also called HFCs. Both give home loans, but they are not the same in the details. Here is a simple side-by-side view to help you choose.
What's the Difference?
Public sector banks, private sector banks, and small finance banks are set up to accept deposits from people. They have lots of services as well. They can offer savings products and also lending, like loans.
HFCs are not the same as banks. They are non-bank entities dealing mainly with housing finance. Instead of relying on everyday savings accounts, they usually get funds through borrowings, through bonds, and through other deposits. Some examples are LIC Housing Finance, PNB Housing Finance, and Bajaj Housing Finance. HDFC Ltd’s later successors are also in this space.
HFCs fall under rules set by the Reserve Bank of India. The RBI has been watching them after the National Housing Bank’s role changed.
Interest Rates
Banks can look a bit better on interest rates. This is more true for public sector banks. One reason is that they often get deposits at a lower cost.
Retail loans with a floating rate usually track a common market reference. For example, many are linked to the repo rate. When the benchmark moves, the loan rate tends to move too, in a clear way.
HFCs may price their loans slightly higher. Still, they do run limited offers. Those deals can narrow the gap. Even a small change like 0.25% can matter over many years. So check the overall loan cost. Do not focus only on the headline rate.
Eligibility and Flexibility
Here HFCs are often a good match. They are easier to work with for:
Self-employed persons or persons with irregular income
Borrowers with less credit history or weaker credit
Homes in semi-urban locations, especially with tricky paperwork
Typically, banks have tighter credit-check and document-review criteria. That means some close-to-a-match cases will be rejected.
Processing Speed and Service
HFCs generally process loan files faster. They often have shorter approval processes, so the cash may be in your hands quicker.
Banks are slower, particularly public sector banks. They may require further levels of approval.
Still, speed can differ depending on how you relate to a bank. If you already have a salary or savings account there, it can be quicker. You may also get a better rate of interest in some cases.
Fees and Charges
Compare these carefully:
Other possible fees related to the loan amount. These can be taken as a share of what you borrow. Some loans may charge for paying early or for foreclosure. This is more common with floating-rate loans for people, though it is usually not allowed. Still, you should confirm what your contract says. You might also see legal fees and technical valuation costs. These are for paperwork and for the property value check. There can be charges if you want to switch the interest rate. Or if you want to change the loan type to something else.
Other Factors to Weigh
Loan amount and term: Both allow for long terms, but the cap may differ.
Transferring the loan later: If you find a better rate, you could be able to transfer your balance.
Online Access: Most HFCs and private banks have good apps for updates and paperwork.
Bank help: Check the ratings and see if there are any branches near you.
Which Should You Choose?
Pick a bank when your pay is steady, your credit record is good, and you want the smallest interest rate, with the reassurance that comes from a bigger company.
Go with an HFC if your income changes from month to month, your credit is just okay, or you need a quicker decision and more room in the requirements.
Final Thoughts
There is no single best lender for everyone. What works for you depends on your income source, your credit rating, the home you want, and what matters most to you.
Try to get offers from at least three different lenders. Make sure you request a complete list of charges. Then plug the numbers into an EMI calculator so you can see the full repayment amount.
Since rates and rules can shift, double-check the latest terms with the lender itself before you commit.
.webp)
.webp)