How to Get a Home Loan?
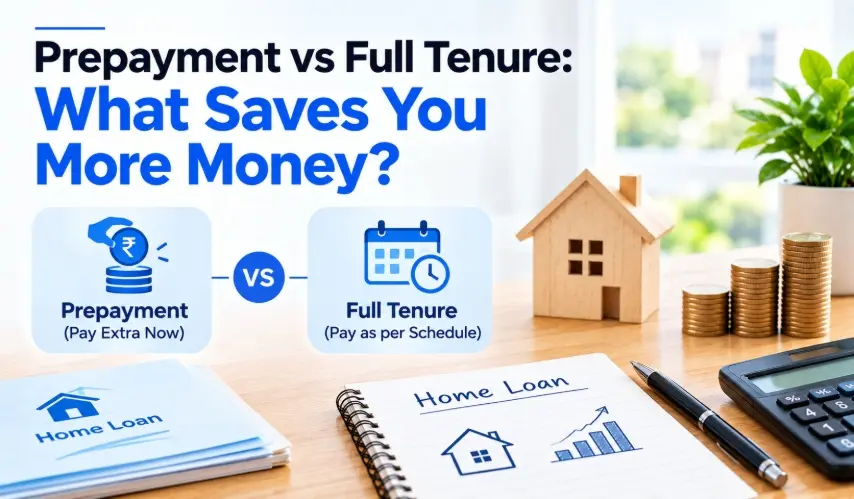
Prepayment vs Full Tenure: What Saves You More Money?
Taking a home loan is not just about the EMI each month. The interest charged on the loan runs for the entire tenure. Over time, that property loan interest rate can add a lot to what you finally pay for the home.
So some borrowers think about paying the loan early instead of sticking to the original repayment plan. The next question is simple: which one helps you spend less, making a prepayment or continuing until the end of the tenure?
What Is Home Loan Prepayment?
By paying more on your home loan, you are applying more money to the balance before your next scheduled repayment date. Some people do this as a one-off payment. Others raise their EMI amount so the loan balance drops faster. Say you get a bonus at work or an annual incentive.
If you have extra cash saved up, you can use part of it to pay down the home loan principal. The lender will normally charge you interest on the amount you borrow. If you clear the balance early, you will end up paying less interest.
What Happens If You Continue for the Full Tenure?
This means that you can pick the entire period of the loan and pay the same various monthly installment without worrying about its early repayment. For many people, this means a good budgeting practice since EMI remains fixed.
However, the larger the period, the higher the interest payments. For example, if someone borrows ₹50 lakh for 20 years, they will have to pay much larger interest costs in addition to the principal sum.
The amount of interest will depend on things like bank interest, the amount of money borrowed and the tenure.
Prepayment Can Reduce Your Total Interest
Imagine you still have a few years left on your loan. If you pay a large extra amount now, the balance you owe drops. With a smaller balance, the home loan interest rates you are charged for the rest of the loan term can fall too.
You can then choose between:
Bring down your loan term, but try to keep the EMI close. Or you can reduce your EMI, with the remaining term remaining more or less the same. If your main aim is to cut down on interest you will generally do better by shortening the loan term. Because you pay back the principal faster.
Should You Use All Your Savings for Prepayment?
You can choose the complete tenure of the loan and continue paying the same EMI each month without worrying about paying off your loan completely. For many people this means budgeting wisely as EMI remains constant.
But longer durations mean higher interest costs. For example, a ₹50 lakh home loan lasting for 20 years will incur much bigger interest payment on top of the capital amount.
The final figure would depend on factors like the home loan interest rate, the amount of loan taken and loan tenure.
Prepayment vs Full Tenure: Which Costs Less?
One of the key benefits of making prepayments on your loans is that you will end up paying a lesser sum of interest. In layman’s terms, when you make a payment that reduces the loan amount, there’s not as much interest that the lender can charge. This will hold true, provided that you have incurred very few charges and you have not missed out on any chances to make use of your funds.
Even so, the best move for you is not always the same. It will depend on how much cash you have each month, how much you can save, where else you may invest and what you want to achieve financially.
Final Takeaway
You are not locked into the first repayment plan for a home loan. If your finances get better, you can change course. Paying more than required at the right time may lower the loan amount you still owe. It can also cut the time left on the loan. In many cases, it can reduce the interest you pay.
Before you send extra money, review what your lender allows. Look at their rules for extra payments. Then work out how much interest you might save with your plan. Also make sure you still have enough cash set aside for emergencies.
The aim is not just to end the home loan fast. The point is to handle your money so the total cost stays lower, while your day to day life stays stable.
.webp)