How to Get a Home Loan?
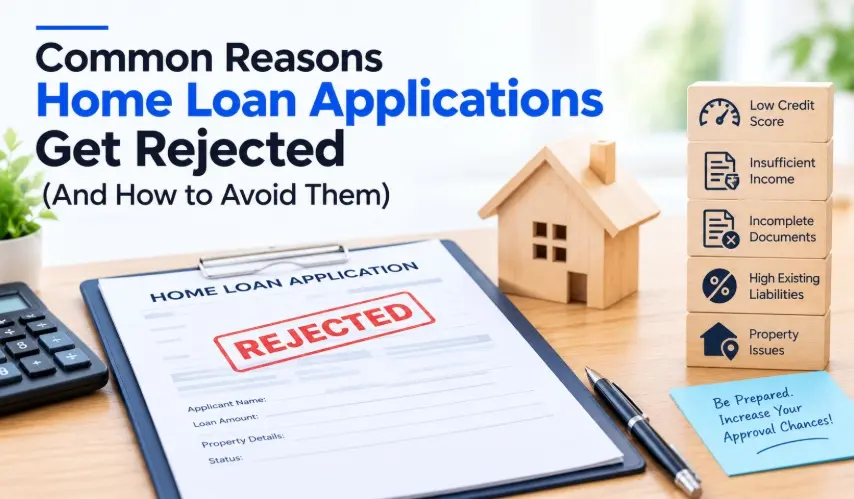
Common Reasons Home Loan Applications Get Rejected (And How to Avoid Them)
It can feel crushing when your home loan application gets turned down, mainly after you think you found the right place. Still, most denials are not just luck or bad timing. They tend to come from a few problems you could have fixed. If you learn what lenders look for and run a loan eligibility check before you apply, you can cut down on delays, reduce stress, and avoid that letdown. Next, let’s go over the usual reasons loans get rejected, and what you can do to lower the risk.
1. Low Credit Score
Lenders usually look at your CIBIL or credit score first. If your score is under 650 to 700, many lenders take it as a sign that you might not repay on time.
How to avoid it: Look at your credit score before you submit an application through. Clear any money you owe. Try not to apply for several loans in a short time. Also keep your credit record steady for about 6 to 12 months before you apply.
2. Low income or high debt to income ratio
Banks verify whether your income can comfortably support the EMI. They also look at your other monthly bills. If your debt-to-income level is high, getting the loan is much harder.
How to avoid it: Calculate home loan eligibility before you submit an application. Start with an online calculator so you can see the loan amount you may be able to get. Look at your income and any current debts. This way, you choose a sensible figure and do not ask for more than you likely qualify for.
3. Erratic work history or employment
If you switch jobs frequently or have not been at your current job very long, lenders may get nervous. They will tend to look closely at the stability of your income. This worry can be stronger when you are applying as a salaried worker.
How to avoid it: Wait until you have been in your current role for at least 1 to 2 years, if that is possible. If you work for yourself, it helps a lot when your business earnings stay steady for the last 2 to 3 years.
4. Incomplete or Incorrect Documentation
Rejections or delays often happen for simple reasons. A file might be missing. Some names might not match on different papers. Other times, a form is left incomplete.
How to avoid it: Check every document a second time, as well as the little things. Organize everything carefully. Open the documents in the correct order and verify that they work correctly. Examine all the printouts, making sure that no documents are missing. While verifying IDs of each individual, you should compare all documents one by one. If you spot any irregularities, stop what you are doing and verify everything again.
5. Property Legal Issues
The lender can usually decline the loan application if there are ambiguous ownership records for the property, litigation matters, or illegal construction activities. This is for possible legal risk avoidance.
How to avoid it: Have an attorney review the documents on the property before you close. This entails, among other things, the title deed, encumbrance certificate, and approved building plan.
6. Too Many Loan Applications at Once
If you apply for loans from several lenders simultaneously, your credit score you have can suffer from it. This could also create the impression of your being short on cash and instill uncertainty in the lenders.
How to avoid it: Make sure you are eligible for a home loan with a couple of lenders before applying for one. Compare the terms they provide and apply to only one lender after you have chosen the best offer.
7. Existing loans and heavy EMI burden
Some lenders will ask if you can afford to pay an extra EMI if you already have loans.
How to avoid it: Don’t start any new debts until you’ve done that. If you can’t pay them off right now, choose a loan that you have more time to pay off. This can help ease the pressure on the EMI.
Final Thoughts
If your first application failed, take a breath. Review your numbers, check your paperwork, and see what options are still open. It is more like a warning sign. If you look closely at your home loan eligibility, there are many sites to have emi calculator home loan fix weak spots in your credit, and double-check your papers, your odds of getting approved go up.
Before you submit anything, spend a few minutes checking your home loan eligibility online. This quick check can prevent a run of bad outcomes. It also helps you move closer to buying the place you want.
.webp)