How to Get a Home Loan?
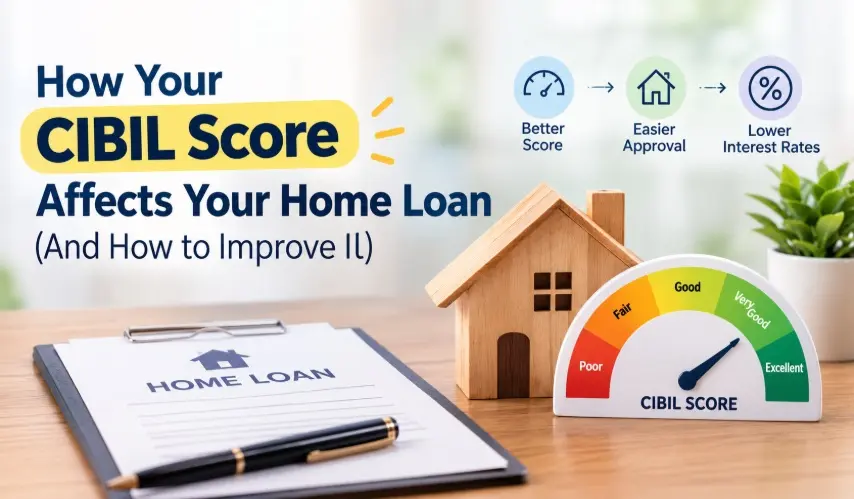
How Your CIBIL Score Affects Your Home Loan (And How to Improve It)
When you apply for a home loan, one thing matters a lot. Your cibil score required for home loan. This score is a three digit number. Most of the time it sits between 300 and 900. Many lenders view 750 and above as a good sign. Banks look at it to see how you managed credit in the past. So the score can play a role in whether the loan gets approved. It can also affect the interest rate you end up with.
Why Your CIBIL Score Matters
If you are looking for a loan, lenders check your CIBIL Score to analyze the risk. A higher score means you have disciplined repayment behavior and are a ‘safer’ borrower. The lower the score, the more likely payments have been missed, or credit is being used a lot, which is a red flag.
Great credit: 750 and up. You usually get the best rates. Decisions can be fast too.
Okay credit: 650 to 750. It can be approved still. Rates may be higher than the best tier.
Bad credit: under 650. Approval can be tough. If you are approved, the terms often cost more, with higher rates and worse conditions.
How It Affects Your Home Loan
Your approval chances are not great if the score is low. In some cases, they will reject the application even if you earn a decent income.
Your interest rate can move with your score. A minor change may adjust the rate, which can shift your EMI and the full repayment total over a long period, like 15 to 20 years.
The loan amount can also shrink. If the score gives red flags about repayment, lenders may approve less than what you asked for.
How to Improve Your CIBIL Score
1. Timely payment of bills and EMIs
Your credit score is based on your payment history, more than anything else. Use reminders or turn on auto-pay so you do not miss dates.
2. Take a lower percentage of the credit available to you
Keep your credit use under 30% of what you can spend. If you charge close to the limit, some lenders may treat it as a bad sign.
3. Apply for fewer loans at a time
A hard inquiry can drop your score for a short time. If you apply to many lenders quickly, the impact can be worse than you expect.
4. Keep a healthy mix of credit
There’s help in the form of secured credit (home and car loans) and unsecured credit (credit cards and personal loans). Just make sure you manage it well.
5. Check your credit report regularly
Errors in your report can result in your score being unfairly dropped. Check out from time to time and object to any wrong details straight away.
6. Do not shut old credit accounts
Older accounts help your credit history stay longer. Keep them open and use them only when it makes sense.
Final Thoughts
A cibil score for home loan is more than a single figure. It shows how you handle money and it can affect your home loan process. If you learn what makes the score change, and if you work on it early, you may get quicker approval. You may also see better loan pricing and save more across the loan term. Start looking at your score now, before you begin searching for a home.
.webp)